Car Insurance: Gen Z Pays the Biggest Markup in These States (and for These Models)

Gen Z pays up to 42% above the average for car insurance, depending on the state. In three states and Washington, D.C., Gen Z drivers pay more than $4,000 per year on average for full coverage.

Matt Brannon
Writer: Matt BrannonEconomic Analyst and Licensed Insurance Agent

Qualifications:
  • Personal linese licensed insurance agent

  • 4+ years writing about insurance and finance topics


Matt is an economic analyst for Compare.com. He's been widely quoted in numerous media outlets for his insurance reporting.

Nick Versaw
Editor: Nick VersawSenior Managing Editor

Qualifications:
  • 10+ years writing and editing insurance content

  • Published in Washington Post, LA Times, and more


Nick leads Compare.com's editorial team in creating helpful, easy-to-understand content about insurance and personal finance.

Published

Why You Can Trust Compare.com: At Compare.com, it’s our mission to find simple ways to help our customers save money on the things they need. While we partner with some of the companies and brands we talk about in our articles, all of our content is written and reviewed by our independent editorial team and never influenced by our partnerships. Learn about how we make money, review our editorial standards, and reference our data methodology to learn more about why you can trust Compare.com.

Car insurance rates have jumped 44% in the past five years, according to Compare.com data. The current national average premium for a full-coverage policy is $2,237 per year, but that cost is often much higher for younger drivers. New data from Compare.com shows Gen Z drivers pay 27% more than the average American for full-coverage car insurance, adding up to nearly $600 per year in additional costs.

Car insurance companies often charge higher premiums to drivers more likely to file a claim or have one filed against them, since it could lead to a large payout. And Gen Z, relative to other age groups, fits that description.

Gen Z drivers report about twice as many accidents and four times as many speeding tickets as baby boomers. That explains why the typical Gen Zer pays $2,835 annually for full coverage, according to Compare.com’s proprietary database of 58 million car insurance quotes.

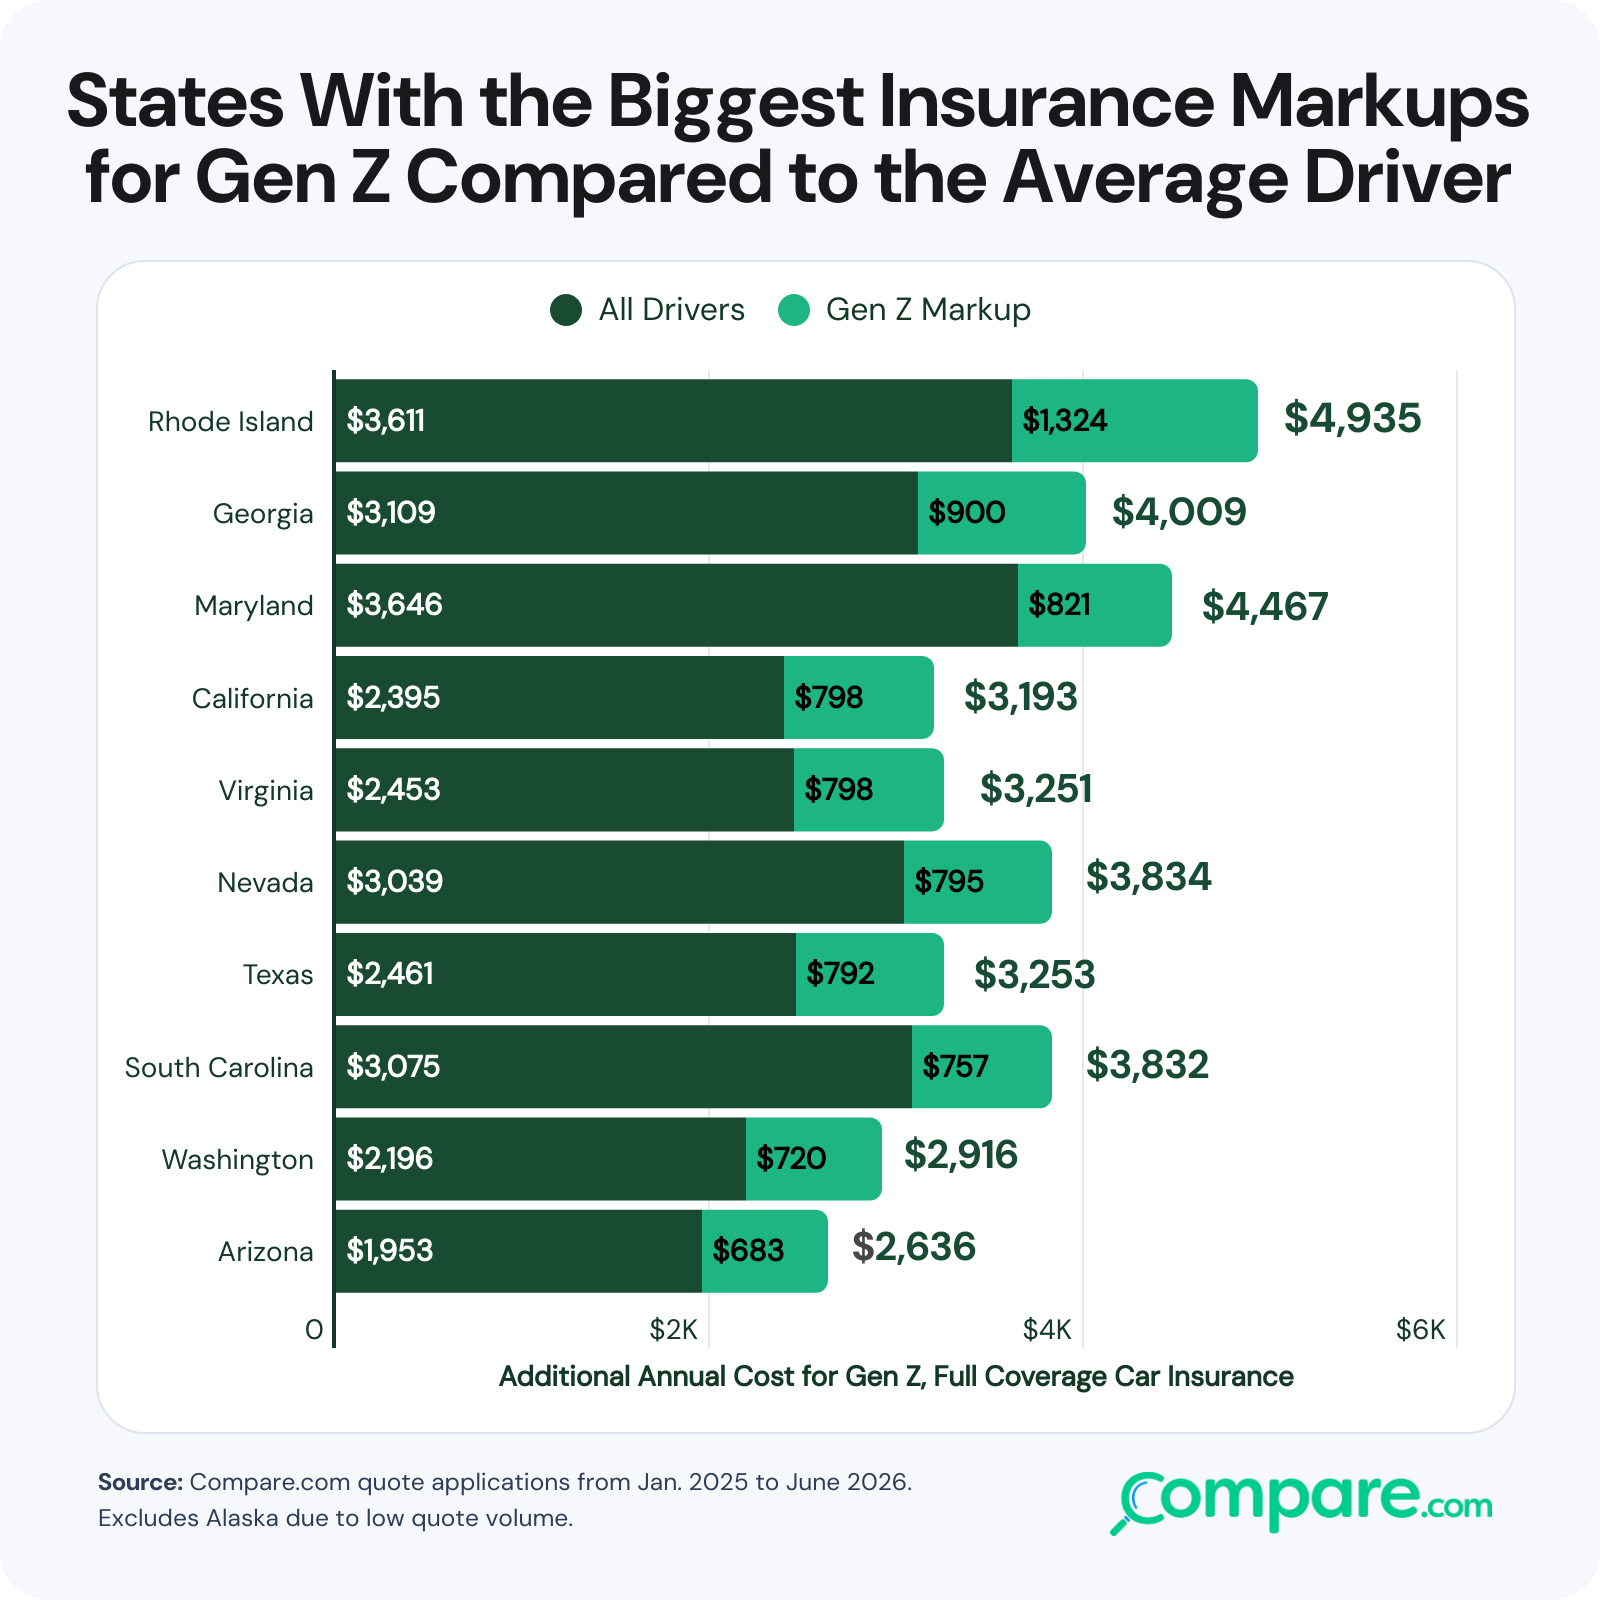
In some states, young drivers pay an even larger markup. In Rhode Island, Gen Z drivers pay $4,935 annually, a staggering $1,324 more than the average Rhode Island driver.

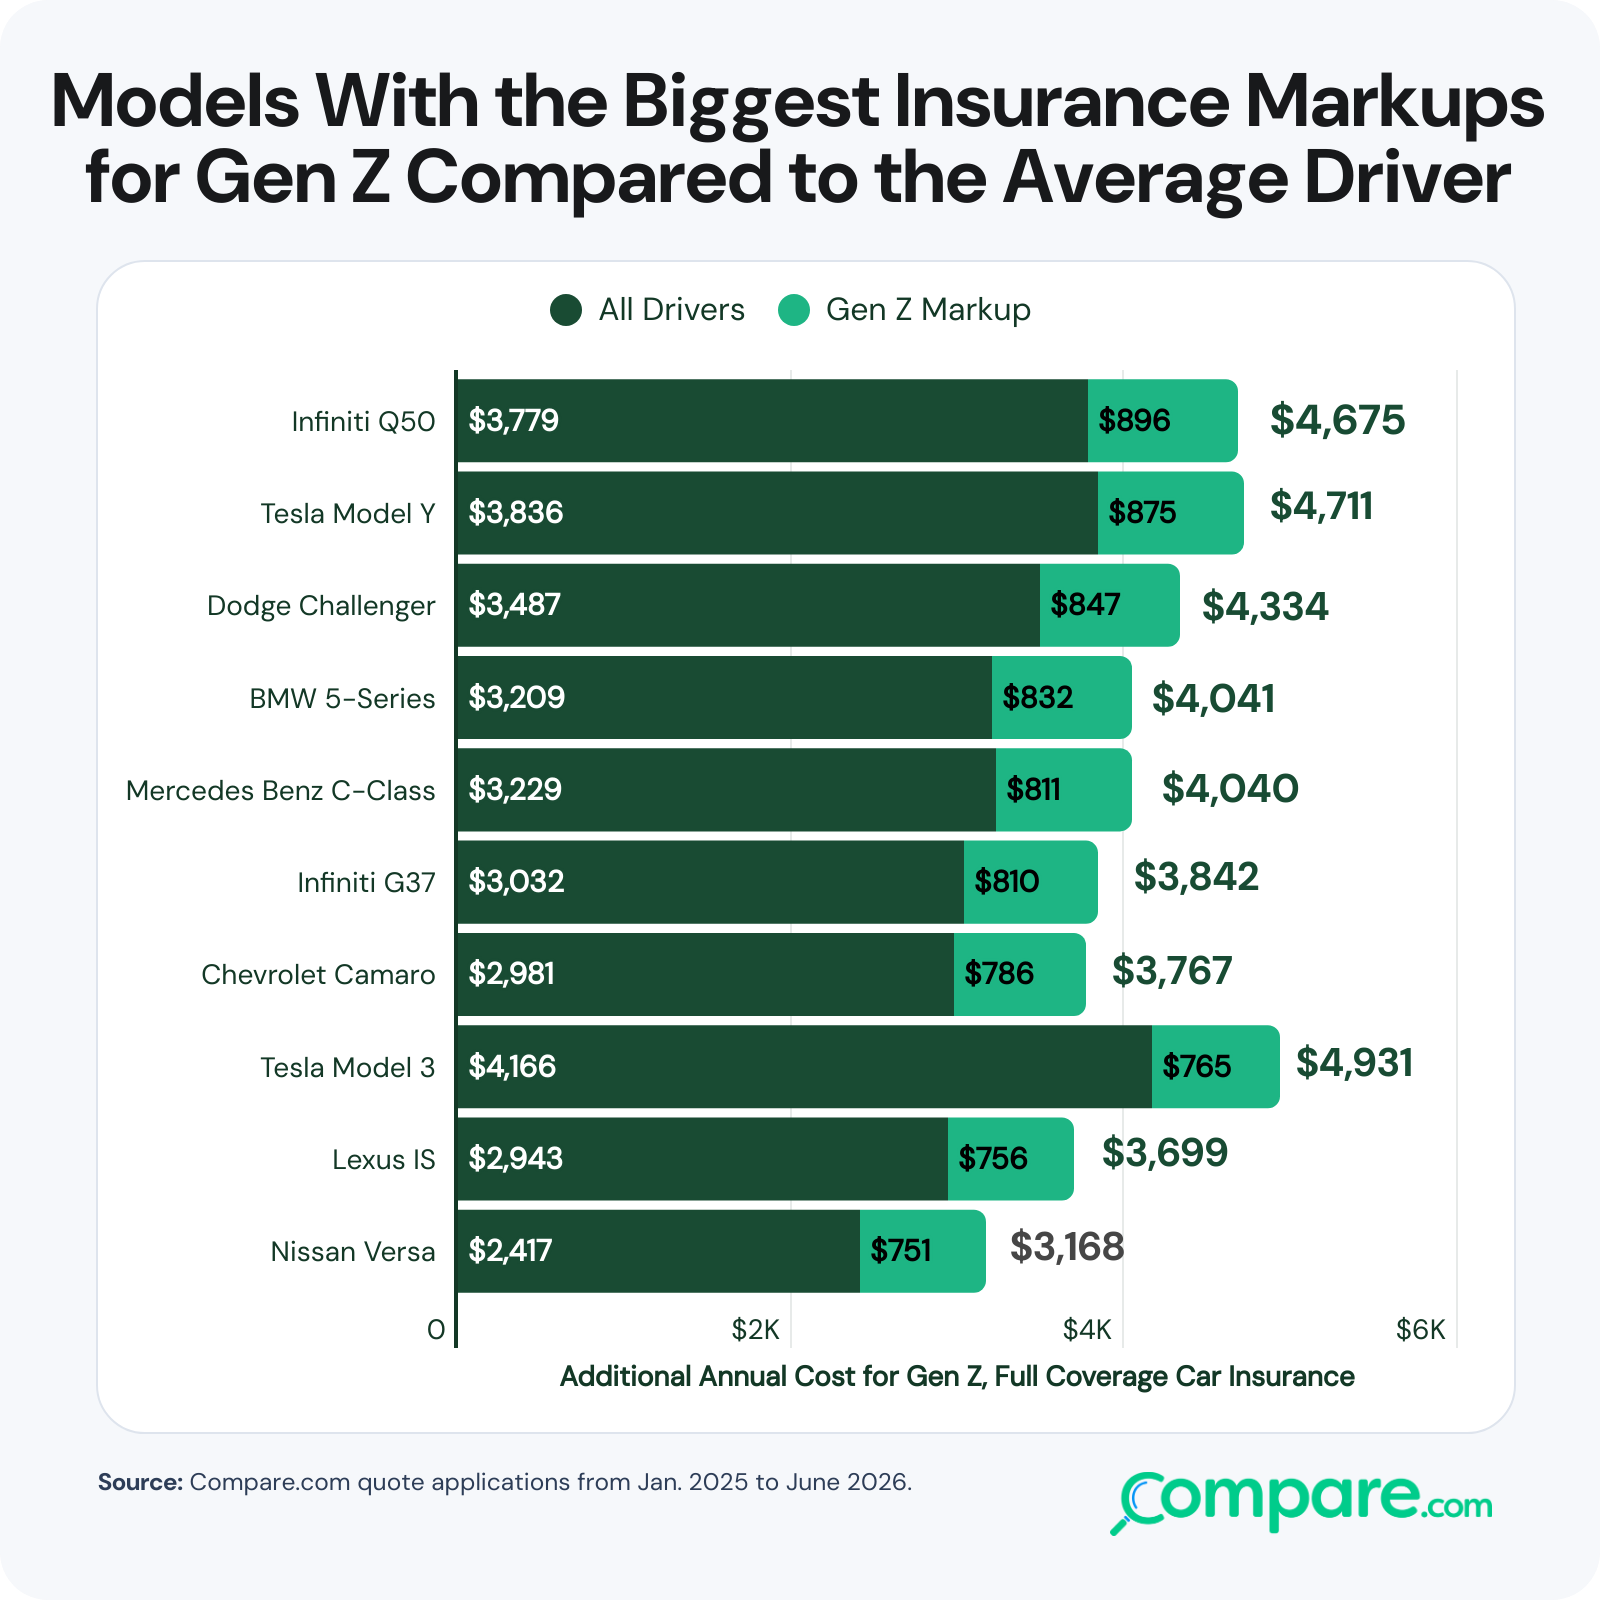
In addition to a driver’s location, the type of car they drive can also have a big effect on their insurance premiums. The mainstream car with the biggest premium penalty for Gen Z drivers is the Infiniti Q50, with young drivers paying an extra $896 annually for full coverage compared to the average driver.

To better illustrate car insurance pricing for Gen Z drivers, Compare.com reviewed insurance applications across 49 states and Washington, D.C., as well as 89 popular car models, to determine the most expensive vehicles and states for Gen Z car insurance.

Key Findings

  • Rhode Island is the most expensive state for Gen Z car insurance. There, Gen Z drivers pay an average of $4,935 annually for full coverage, 37% more than the average driver in the state.

  • In Maine, Gen Z drivers pay 42% more than the average driver for full coverage ($1,823 vs. $1,280), the largest percentage gap of any state. Idaho follows at 41% more.

  • When comparing car models, Gen Z drivers pay the largest insurance markup for the Infiniti Q50, at an average of $4,675 annually for full coverage, $896 more than the average driver for the same model.

  • Overall, the most expensive car models for Gen Zers to insure are the Tesla Model 3 ($4,931), Tesla Model Y ($4,711), and the Infiniti Q50 ($4,675).

States Where Gen Z Pays the Biggest Insurance Markup Over Average Drivers

Younger drivers are more likely to cause car accidents than older drivers, but that isn’t the only factor working against them in car insurance pricing. Younger drivers are also less likely to qualify for certain discounts, like bundling policies or being a homeowner.[1]

Pricing is also highly dependent on location, as insurers face higher losses in some states than others. The most expensive places for Gen Z to insure a vehicle are often in the Northeast, a region with relatively high traffic congestion and high auto repair costs.

Car Insurance Markup for Gen Z By State, in Dollars (Annual Cost of Full Coverage)

State
Gen Z Premium Over Average Drivers ($)
Gen Z Premium Over Average Drivers (%)
Average Annual Cost, Gen Z
Average Annual Cost, All Drivers
Alabama$50830%$2,215$1,707
Arkansas$44524%$2,274$1,829
Arizona$68335%$2,636$1,953
California$79833%$3,193$2,395
Colorado$63624%$3,239$2,603
Connecticut$57122%$3,223$2,652
District of Columbia$54114%$4,422$3,880
Delaware$63921%$3,739$3,100
Florida$46318%$3,017$2,554
Georgia$90029%$4,009$3,109
Hawaii$735%$1,601$1,528
Iowa$33625%$1,667$1,331
Idaho$53241%$1,837$1,305
Illinois$64333%$2,573$1,930
Indiana$56336%$2,109$1,546
Kansas$53529%$2,366$1,831
Kentucky$56124%$2,863$2,302
Louisiana$67127%$3,175$2,504
Massachusetts$42925%$2,119$1,690
Maryland$82123%$4,467$3,646
Maine$54342%$1,823$1,280
Michigan$48415%$3,712$3,229
Minnesota$57826%$2,780$2,202
Missouri$54125%$2,706$2,165
Mississippi$64529%$2,856$2,211
Montana$31617%$2,200$1,883
North Carolina$26519%$1,638$1,373
North Dakota$23920%$1,414$1,175
Nebraska$54235%$2,089$1,547
New Hampshire$29529%$1,313$1,019
New Jersey$52518%$3,448$2,923
New Mexico$45928%$2,091$1,632
Nevada$79526%$3,834$3,039
New York$60321%$3,443$2,840
Ohio$45632%$1,860$1,404
Oklahoma$55127%$2,574$2,023
Oregon$49326%$2,369$1,876
Pennsylvania$42022%$2,350$1,930
Rhode Island$1,32437%$4,935$3,611
South Carolina$75725%$3,832$3,075
South Dakota$44424%$2,278$1,834
Tennessee$53934%$2,121$1,582
Texas$79232%$3,253$2,461
Utah$41023%$2,183$1,773
Virginia$79833%$3,251$2,453
Vermont$57235%$2,198$1,626
Washington$72033%$2,916$2,196
Wisconsin$46931%$1,985$1,516
West Virginia$52429%$2,357$1,833
Wyoming$20218%$1,320$1,118

1. Rhode Island

  • Average Gen Z insurance premium: $4,935 per year

  • Average insurance premium for all drivers: $3,611 per year

  • Average premium markup for Gen Z: $1,324 per year (+37%)

Rhode Island has the highest car insurance rates for Gen Z drivers of any state. It also has the largest dollar gap between what average drivers and Gen Zers pay, with younger drivers spending an additional $1,324 per year for full coverage.

Premiums in the state are already among the highest nationally for all drivers, largely due to the state’s higher percentage of urban residents.[2] Cities typically have more traffic, accidents, and claims, which leads to higher premiums.

Rhode Island also has a high cost of living, which can make claims more expensive. And since Gen Z drivers are more likely to file claims, according to Compare.com data, insurers charge them higher premiums to offset higher financial losses.

2. Georgia

  • Average Gen Z insurance premium: $4,009 per year

  • Average insurance premium for all drivers: $3,109 per year

  • Average premium markup for Gen Z: $900 per year (+29%)

Georgia drivers of all ages have seen their car insurance premiums increase by about 40% over the past three years, as insurers post above-average losses in the state. Gen Z drivers aren’t excluded from that trend.

Georgia is one of three states, plus Washington, D.C., where young drivers pay more than $4,000 per year for car insurance. However, lawmakers in 2025 passed legislation to reduce high legal costs for insurers, which could lower claims expenses. Over time, they could pass those savings on to drivers through lower premiums.[3]

3. Maryland

  • Average Gen Z insurance premium: $4,467 per year

  • Average insurance premium for all drivers: $3,646 per year

  • Average premium markup for Gen Z: $821 per year (+23%)

Gen Z drivers in Maryland pay an average of $821 more for full-coverage car insurance each year compared to the typical Maryland driver, the third-largest markup nationally. The state shares many of Rhode Island’s risk factors, leading to higher overall car insurance rates, including for younger drivers.

Insurers generally charge higher premiums in areas where claims cost them more. Maryland ranks among the states with the highest frequency of bodily injury claims, which are generally the most expensive type of claim for insurers.[4]

4. California

  • Average Gen Z insurance premium: $3,193 per year

  • Average insurance premium for all drivers: $2,395 per year

  • Average premium markup for Gen Z: $798 per year (+33%)

Young drivers in California pay one of the largest markups nationally, at $798, despite state law barring insurers from using age as a factor in rate-setting. That’s because state law also requires insurers to weigh driving experience more than most factors.[5]

In practice, that means Gen Z drivers pay more for having fewer years of driving experience since less-experienced drivers statistically get into more accidents.

More recently, state insurance officials have suggested barring insurers from using marital status as a factor, which could improve rates for single drivers. And Gen Zers could benefit most since they’re less likely to be married than other generations.[6]

5. Virginia

  • Average Gen Z insurance premium: $3,251 per year

  • Average insurance premium for all drivers: $2,453 per year

  • Average premium markup for Gen Z: $798 per year (+33%)

In Virginia, Gen Z drivers pay nearly $800 more each year for full-coverage car insurance than the average resident. Age aside, drivers in the state already pay about 10% more than the national average due to Virginia’s increased rate of collision claims, which is about 4% above the national average.[4]

Prices have also gone up in Virginia since the state raised its minimum coverage requirements in 2025.[7]
Car Models With the Biggest Insurance Markups for Gen Z Drivers

People who drive expensive cars tend to pay more for car insurance, largely because their cars have costlier, harder-to-replace parts. And insurers consider the cost of repairs and replacement parts when they quote car insurance premiums.

Compare.com data also shows that electric vehicles (EVs) tend to face higher car insurance premiums. Repair costs for EV batteries often run high, in part because of fewer available EV technicians compared to traditional mechanics.[8]

Among popular car models, the two most expensive cars for Gen Z drivers to insure overall are both Tesla EVs. Even so, Gen Zers pay the biggest average markup for the Infiniti Q50.

1. Infiniti Q50

  • Average Gen Z insurance premium: $4,675 per year

  • Average insurance premium for all drivers: $3,779 per year

  • Average premium markup for Gen Z: $896 per year (+24%)

As a luxury sedan, the Q50 is generally more expensive to insure than a more modest vehicle. Before Infiniti stopped making the model in 2024, a new Q50 had a starting MSRP of $43,050.[9] In addition to a high purchase price, insurance claims are both more frequent and more expensive for the Q50 compared to the typical passenger car, according to data from the Highway Loss Data Institute.[10] 

Gen Z drivers pay nearly $900 more annually for full coverage than the average Q50 driver.

2. Tesla Model Y

  • Average Gen Z insurance premium: $4,711 per year

  • Average insurance premium for all drivers: $3,836 per year

  • Average premium markup for Gen Z: $875 per year (+23%)

Gen Z drivers who own a Model Y pay over $4,700 per year for full-coverage car insurance. That’s more than double what the typical U.S. driver pays ($2,237).

Repair costs play a big role in that pricing gap, since EVs cost around 15% more to repair than gas-powered cars.[11] Insurers generally pass those higher costs on to drivers through higher premiums.

3. Dodge Challenger

  • Average Gen Z insurance premium: $4,334 per year

  • Average insurance premium for all drivers: $3,487 per year

  • Average premium markup for Gen Z: $847 per year (+24%)

Muscle cars like the Dodge Challenger tend to be more expensive to insure, in part because of higher accident rates. Compare.com data shows that Challenger drivers report more recent accidents, tickets, and DUIs than the typical driver.

The two-door coupe is also a frequent target for thieves. On a per-car basis, it’s about six times more likely to be stolen than the average passenger car.[12]

4. BMW 5 Series

  • Average Gen Z insurance premium: $4,041 per year

  • Average insurance premium for all drivers: $3,209 per year

  • Average premium markup for Gen Z drivers: $832 per year (+26%)

The BMW 5 Series is a relatively expensive car with a high accident rate, a common recipe for high insurance premiums. The purchase price for new models starts at nearly $62,000.[13]

Dangerous driving also contributes to higher pricing. About 6.8% of 5 Series drivers report an at-fault accident in the last three years, compared to just 4.8% of all drivers, according to Compare.com data. For Gen Z 5 Series drivers, that figure jumps to 10.5%.

5. Mercedes-Benz C-Class

  • Average Gen Z insurance premium: $4,040 per year

  • Average insurance premium for all drivers: $3,229 per year

  • Average premium markup for Gen Z drivers: $811 per year (+25%)

Luxury cars nearly always come with higher insurance rates, since they’re typically more expensive to repair and replace. If you pair a luxury vehicle with an inexperienced driver, the chance of insurers paying expensive claims increases substantially.

In fact, insurers are so wary of young C-Class drivers that they charge Gen Z owners with a clean record nearly as much as C-Class owners of any age who reported an at-fault accident in the past three years ($4,040 vs. $4,251).

How Gen Z Drivers Can Save on Car Insurance

For younger drivers, it’s safe to expect higher car insurance premiums than the average driver. But that doesn’t mean they must simply accept an expensive policy.

Here are some of the most effective strategies Gen Zers can use to prevent overpaying for car insurance:

  • Compare prices across insurers. Regardless of age, drivers shouldn’t assume the insurance company that gave them the best deal three years ago will still offer the lowest rates. Once or twice a year, drivers should spend a few minutes getting quotes from multiple insurance companies. By comparing insurers, drivers can often find a policy similar to their existing coverage for a fraction of the cost.

  • Seek out discounts. Some drivers could be surprised to learn how many discounts certain insurers offer. Some insurers offer discounts for maintaining low mileage, enrolling in auto pay, driving a new car, installing anti-theft measures, and many other scenarios.

  • Drive safely. After buying a car insurance policy, it’s important to avoid giving insurers reasons to raise your premiums. That means driving safely and defensively. Compare.com research shows that a single at-fault accident leads to a 34% increase in a driver’s premium, on average.

Methodology

Compare.com data scientists reviewed more than 58 million rates using our proprietary database, quoted via integrations with partnering insurance companies. Insurance applications come from all 50 states and Washington, D.C., and contain information on the precise coverage specifications within each policy quote that drivers see. Alaska was excluded from the analysis due to lower quote volume.

Insurance premium data in this report comes from insurance applications dated January 2025 to June 2026. Compare.com examined the 89 most popular vehicles for Gen Z drivers.

The full-coverage car insurance premiums in this report reflect the median insurance cost for drivers ages 20 to 29, unless noted. Annual prices use two-year rolling medians to mitigate market volatility in recent years.

Full-coverage premiums represent policies with bodily injury limits between state-minimum requirements and $50,000 per person and $100,000 per accident; property damage coverage between $10,000 and $50,000; and comprehensive and collision coverage with deductibles of $1,000.

Model
Gen Z, Average Annual Cost
All Drivers, Average Annual Cost
Gen Z Markup
Audi A4$3,581$2,844+$737 (26%)
BMW 3 Series$3,559$2,832+$727 (26%)
BMW 5 Series$4,041$3,209+$832 (26%)
Chevrolet Blazer$3,023$2,497+$526 (21%)
Chevrolet Camaro$3,767$2,981+$786 (26%)
Chevrolet Cruze$2,804$2,260+$544 (24%)
Chevrolet Equinox$2,633$2,123+$510 (24%)
Chevrolet Impala$2,759$2,313+$446 (19%)
Chevrolet Malibu$3,131$2,535+$596 (24%)
Chevrolet Silverado$2,914$2,264+$650 (29%)
Chevrolet Tahoe$2,694$2,269+$425 (19%)
Chevrolet Trailblazer$2,726$2,228+$498 (22%)
Chevrolet Traverse$2,592$2,206+$386 (17%)
Chevrolet Trax$2,833$2,247+$586 (26%)
Chrysler 200$2,792$2,298+$494 (21%)
Chrysler 300$3,512$2,763+$749 (27%)
Dodge Challenger$4,334$3,487+$847 (24%)
Dodge Charger$4,098$3,384+$714 (21%)
Dodge Durango$3,034$2,491+$543 (22%)
Dodge Journey$2,569$2,176+$393 (18%)
Dodge Ram 1500$2,445$1,976+$469 (24%)
Ford Edge$2,371$1,951+$420 (22%)
Ford Escape$2,418$1,951+$467 (24%)
Ford Explorer$2,537$2,116+$421 (20%)
Ford F-Series Pickup$2,993$2,322+$671 (29%)
Ford Focus$2,667$2,130+$537 (25%)
Ford Fusion$2,916$2,397+$519 (22%)
Ford Mustang$3,671$2,982+$689 (23%)
Ford Ranger$2,568$2,017+$551 (27%)
Ford Taurus$2,812$2,191+$621 (28%)
GMC Acadia$2,565$2,135+$430 (20%)
GMC Sierra$3,004$2,311+$693 (30%)
GMC Terrain$2,598$2,042+$556 (27%)
Honda Accord$3,041$2,471+$570 (23%)
Honda Civic$3,076$2,556+$520 (20%)
Honda CR-V$2,421$1,965+$456 (23%)
Honda HR-V$2,838$2,331+$507 (22%)
Honda Odyssey$2,127$1,930+$197 (10%)
Honda Pilot$2,425$2,089+$336 (16%)
Hyundai Accent$2,859$2,277+$582 (26%)
Hyundai Elantra$3,344$2,718+$626 (23%)
Hyundai Santa Fe$2,710$2,238+$472 (21%)
Hyundai Sonata$3,264$2,659+$605 (23%)
Hyundai Tucson$2,765$2,226+$539 (24%)
Infiniti G37$3,842$3,032+$810 (27%)
Infiniti Q50$4,675$3,779+$896 (24%)
Jeep Cherokee$2,727$2,208+$519 (24%)
Jeep Compass$2,701$2,235+$466 (21%)
Jeep Grand Cherokee$2,859$2,327+$532 (23%)
Jeep Patriot$2,417$1,948+$469 (24%)
Jeep Wrangler$2,686$2,166+$520 (24%)
Kia Forte$3,086$2,472+$614 (25%)
Kia K4$3,848$3,264+$584 (18%)
Kia K5$3,716$3,161+$555 (18%)
Kia Optima$3,088$2,535+$553 (22%)
Kia Rio$3,048$2,400+$648 (27%)
Kia Sorento$2,645$2,208+$437 (20%)
Kia Soul$2,676$2,068+$608 (29%)
Kia Sportage$2,793$2,240+$553 (25%)
Lexus ES$3,394$2,678+$716 (27%)
Lexus IS$3,699$2,943+$756 (26%)
Mazda 3$2,901$2,380+$521 (22%)
Mazda 6$2,775$2,292+$483 (21%)
Mazda CX-5$2,448$2,070+$378 (18%)
Mercedes-Benz C-Class$4,040$3,229+$811 (25%)
Nissan Altima$3,519$2,872+$647 (23%)
Nissan Kicks$3,252$2,576+$676 (26%)
Nissan Maxima$3,514$2,802+$712 (25%)
Nissan Murano$2,637$2,112+$525 (25%)
Nissan Rogue$2,871$2,318+$553 (24%)
Nissan Sentra$3,504$2,784+$720 (26%)
Nissan Versa$3,168$2,417+$751 (31%)
Ram 1500$3,239$2,543+$696 (27%)
Subaru Forester$2,218$1,800+$418 (23%)
Subaru Impreza$2,528$2,048+$480 (23%)
Subaru Legacy$2,460$1,975+$485 (25%)
Subaru Outback$2,191$1,769+$422 (24%)
Tesla Model 3$4,931$4,166+$765 (18%)
Tesla Model Y$4,711$3,836+$875 (23%)
Toyota Avalon$2,899$2,343+$556 (24%)
Toyota Camry$3,343$2,734+$609 (22%)
Toyota Corolla$3,305$2,708+$597 (22%)
Toyota Highlander$2,523$2,155+$368 (17%)
Toyota Prius$2,728$2,277+$451 (20%)
Toyota RAV4$2,589$2,128+$461 (22%)
Toyota Tacoma$2,899$2,278+$621 (27%)
Volkswagen Jetta$3,019$2,457+$562 (23%)
Volkswagen Passat$2,791$2,345+$446 (19%)
Volkswagen Tiguan$2,696$2,279+$417 (18%)

Sources

  1. NAHB. "Homeownership Rate Edges Down to 65%."
  2. Visual Capitalist. "Mapping U.S. Urbanization, by State."
  3. The Brunswick News. "Are Georgia’s tort reforms starting to pay off?."
  4. NAIC. "2022/2023 Auto Insurance Database Report."
  5. California Department of Insurance. "Impact Analysis of Weighting Auto Rating Factors to Comply with Proposition 103."
  6. Insurance Journal. "California Insurance Commissioner Proposes End to Marital Status Use in Auto Rates."
  7. Carrier Management. "Four States See Increase in Auto Insurance Liability Limits in 2025."
  8. Insurance Journal. "EVs Head for Junkyard as Mechanic Shortage Inflates Repair Costs."
  9. Infiniti News. "2024 INFINITI Q50 pricing starts at $43,050 MSRP."
  10. HLDI. "Collision losses."
  11. Mitchell. "Plugged-In: EV Collision Insights Q2 2026."
  12. HLDI. "Whole vehicle theft losses."
  13. Kelley Blue Book. "2027 BMW 5 Series."
Matt Brannon
Writer: Matt BrannonEconomic Analyst and Licensed Insurance Agent

Qualifications:
  • Personal linese licensed insurance agent

  • 4+ years writing about insurance and finance topics


Matt is an economic analyst for Compare.com. He's been widely quoted in numerous media outlets for his insurance reporting.

Nick Versaw
Editor: Nick VersawSenior Managing Editor

Qualifications:
  • 10+ years writing and editing insurance content

  • Published in Washington Post, LA Times, and more


Nick leads Compare.com's editorial team in creating helpful, easy-to-understand content about insurance and personal finance.